Key Takeaways
- With U.S. Treasury Bonds at 5%, Wednesday PMIs Will Inform the Story
- AI Security Continues to Be a High Concern
- President Xi Visits DC This Week for Talks with President Trump
What occurs throughout this International Week Forward?
World markets have one other high-stakes week in retailer, showcasing dwell geopolitics—
- A summit between the U.S. and Chinese language presidents in Washington D.C., and
- The United Nations Normal Meeting are happening, towards
- A backdrop of multiplying international crises
In macro information—
- There might be PMI information for the worldwide bond markets to digest
- There’s an necessary central financial institution assembly in Southeast Asia’s largest financial system Indonesia, and
- The controversy about the way to cease AI “wiping out humanity” rages on
Subsequent are Reuters’ 5 world market themes, re-ordered for fairness merchants—
(1) 10-yr U.S. Treasury Yield Reaches 5.0% Rubicon; PMIs Wednesday
Flash buying managers index (PMI) information from the U.S. manufacturing sector touchdown on Wednesday will give the growling international bond markets one thing to chew on.
The ten-year US Treasury yield — a key driver of world borrowing prices and currencies, too — has simply examined the psychologically necessary 5% threshold and the Federal Reserve has simply delivered its first rate of interest hike in additional than three years, so traders are ready to see if something snaps.
However many belongings aren’t buying and selling because the finance textbooks counsel. World shares have barely sagged within the final month and the greenback hasn’t actually risen both, regardless of the rise in Treasury yields.
Nonetheless, it will be courageous to disregard the 10-year yield, contemplating why it has been climbing.
(2) AI Security Considerations Mount Critical Laws Mentioned
AI improvement will stay firmly middle stage as firms, governments and traders all grapple with the more and more apocalyptic warnings in regards to the risks of the rising expertise.
The calls this month by Anthropic’s CEO and different prime AI lab heads to “tempo” its improvement have come amid some dire pronouncements about its potential threats to humanity itself, worries that started to impression the share costs of the semiconductor and so-called hyper-scaler giants on the middle of the increase.
Traders although are actually searching for extra concrete indicators that issues actually will sluggish earlier than declaring the stratospheric two-year rise in AI shares and the associated capital spending over.
President Donald Trump has referred to as the current AI-mageddon warnings a hoax, signaling he will not let builders apply the brakes, whereas European Fee President Ursula von der Leyen desires to get the principle AI gamers to Europe to debate the dangers.
(3) China’s President Xi Jinping Visits DC on a 3-Day State Go to
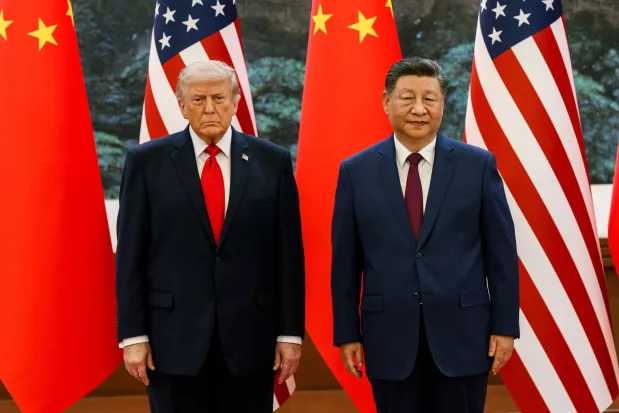
Subsequent week’s headline occasion might be Chinese language President Xi Jinping’s three-day state go to to Washington to fulfill his US counterpart Donald Trump.
The 2 final met in Beijing in Might and have largely had steady relations since a shaky commerce truce final October, however markets might be desirous to see how issues play out right here given every little thing that is unfolded since, particularly concerning the Iran conflict.
US allies in Asia additionally fear Trump could also be tempted to melt his help for Taiwan in return for an financial win forward of US midterms, whereas the fierce US-China AI arms race and the US’s navy buildup in house might be different sizzling matters, given the depth of the 2 nations’ rivalry.
Trump will even maintain a state dinner on the White Home. It is just the second of his present time period and the visitor listing is anticipated to be closely loaded with prime tech chiefs, together with Nvidia CEO Jensen Huang.
(4) The 81st U.N. Normal Meeting Kicks Off. Keep Away from Manhattan!
The 81st UN Normal Meeting Excessive-Degree Week kicks off tomorrow towards a backdrop of deep multilateral paralysis and multiplying international crises and with a summit theme of “Restoring Belief, Managing Transformation.”
The first draw would be the deepening fractures of a fragmenting world order. With deadlocked conflicts in Ukraine and the Center East widening the hole between the West and the International South, the debates will highlight the prices of transactional diplomacy.
The behind-the-scenes horse-trading over who would be the subsequent UN Secretary-Normal will intensify, too, appearing as a proxy battle for future superpower affect.
In the meantime, pressing panels on synthetic intelligence governance, international local weather change threats and sovereign debt mechanisms will take a look at whether or not fragmented states can nonetheless unite on the important thing points, or keep away from a “world of fortresses” that threatens international financial stability.
(5) On Wednesday, Indonesia Central Financial institution’s Newest Coverage Fee Choice
Markets will carefully watch Indonesia’s central financial institution rate of interest resolution on Wednesday after the most recent spherical of modifications within the nation’s prime financial personnel and amid a disaster of confidence of kinds amongst traders.
It is going to be new Governor Destry Damayanti’s second assembly, and the primary since she was formally sworn in as the primary lady to go the central financial institution following July’s shock resignation of earlier Governor Perry Warjiyo. The choice itself is anticipated to be both be a maintain or a small reduce.
It’s going to additionally come only a week after Indonesian President Prabowo Subianto sacked outspoken Finance Minister Purbaya Yudhi Sadewa following a spate of bureaucratic infighting.
Analysts hope changing Purbaya along with his deputy Suahasil Nazara would assist restore some investor confidence within the $1.5 trillion G20 financial system after a string of crises amid long-festering considerations about policymaking, fiscal profligacy and a attainable downgrade of its fairness market to “frontier” standing by index supplier MSCI.
Zacks #1 Rank (STRONG BUY) Shares
Subsequent, I picked three Oil and Gasoline Zacks #1 (STRONG BUY) large-cap shares.
(1) Valero (VLO – Free Report) : This can be a $413 a share oil & gasoline refining inventory, with a market cap of $116.1B
It’s discovered within the Zacks Oil and Gasoline – Refining and Advertising and marketing trade. The inventory holds a Zacks Worth rating of B, a Zacks Progress rating of A, and a Zacks Momentum rating of A.
F12M P/E: 8.6.
Picture Supply: Zacks Funding Analysis
Valero Vitality Company is the biggest impartial refiner and marketer of petroleum merchandise in the US.
It has refineries situated all through the US, Canada and the UK.
Furthermore, Valero is a number one ethanol producer with ethanol crops within the Midwest.
The merchandise of the corporate are bought within the markets of the US, Canada, the UK, Eire and Latin America.
The corporate’s model names are carried by retailers.
The corporate organizes its enterprise by three reportable segments, particularly:
- Refining
- Ethanol and
- Renewable Diesel
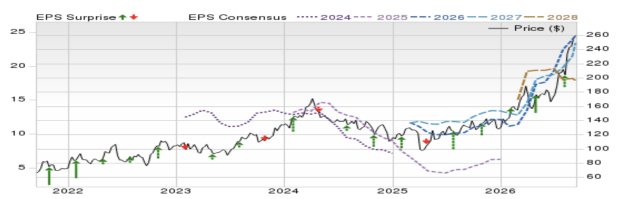
(2) Phillips 66 (PSX – Free Report) : This can be a $274 a share inventory, with a market cap of $105.6B
It’s present in Zacks Oil and Gasoline – Refining and Advertising and marketing trade. The inventory holds a Zacks Worth rating of B, a Zacks Progress rating of A, and a Zacks Momentum rating of A.
F12M P/E: 9.8.
Picture Supply: Zacks Funding Analysis
Phillips 66’s operations incorporate refining, midstream, advertising and specialties, and chemical compounds.
The corporate’s operations embrace processing, transportation, storing and advertising fuels and merchandise all around the world.
The corporate operates by the 4 enterprise segments, particularly, Midstream, Chemical substances, Refining, and Advertising and marketing and Specialties.
- Midstream gathers, processes, transports and markets pure gasoline; and transports, fractionates and markets NGL in the US. As well as, this section transports crude oil and different feedstocks to its refineries and different areas, and delivers refined and specialty merchandise to the market.
- Chemical substances manufacture and markets petrochemicals and plastics on a worldwide foundation.
- Refining buys, sells and refines crude oil and different feedstocks at its refineries.
- Advertising and marketing and Specialties purchases for resale and markets refined merchandise. As well as, this section contains the manufacturing and advertising of specialty merchandise.
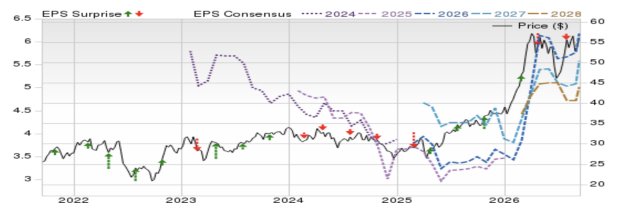
(3) Eni (E – Free Report) : This can be a $55 a share oil and gasoline inventory, with a market cap of $93.3B
It’s discovered within the Zacks Oil and Gasoline – Built-in Worldwide trade. The inventory holds a Zacks Worth rating of A, a Zacks Progress rating of C, and a Zacks Momentum rating of B.
F12M P/E: 9.2.
Picture Supply: Zacks Funding Analysis
Eni SpA, is among the many main built-in vitality gamers on the earth.
Their upstream operations embrace the exploitation and manufacturing of oil and pure gasoline sources. Via midstream actions Eni transports and retailer hydrocarbons. Eni can also be engaged in refining hydrocarbons and distributing the top merchandise.
Other than offering oil & pure gasoline, Eni additionally generates and sells electrical energy.
Eni operates primarily by 3 enterprise segments — Exploration & Manufacturing, Gasoline & Energy and Refining & Advertising and marketing and Chemical substances.
- Via the Exploration & Manufacturing section, Eni exploits and extracts oil and pure gasoline. Eni’s upstream operations additionally embrace companies associated to LNG. Via 2021, Eni managed to drill a number of improvement wells.
- Eni’s International Gasoline & LNG Portfolio section engages in distributing and advertising pure gasoline and liquefied pure gasoline within the wholesale market.
- Eni’s Refining & Advertising and marketing and Chemical substances section is concerned in refining and advertising of petroleum merchandise at retail and wholesale markets.
Key International Macro
The large PMI day is Wednesday.
On Sunday, the Folks’s Financial institution of China (PBoC) set financial coverage. A 3.0% mortgage coverage charge is in place.
On Monday, the Financial institution of Canada (BoC) Governor Macklem and the Reserve Financial institution of Australia (RBA) Governor Bullock gave speeches.
The European Central Financial institution’s (ECB) President LaGarde additionally gave a speech.
On Tuesday, the U.S. Federal Reserve of New York’s Williams offers a speech. Ditto the Fed’s Jefferson and Barkin.
On Wednesday, the Euro Space HCOB manufacturing PMI for September comes out. 52.7 was the prior studying.
The S&P International Manufacturing PMI for Sept. additionally comes out. 53.9 was the prior studying.
Australia’s family unemployment charge for August comes out. 4.5% was the prior studying.
On Thursday, the Swiss Nationwide Financial institution (SNB) units its financial coverage. Their present coverage charge is 0%. There’s a presser.
U.S. New Dwelling Gross sales come out for August. 0.61M is what to anticipate.
New and present properties are 2 distinct segments contained in the U.S. housing market.
You possibly can thank Former Fed Chair Powell’s 2020 and 2021 “QE” cash printing for that.
On Friday, the College of Michigan Shopper Sentiment Index for Sept. comes out. A low 47.8 was the August studying.
Conclusion
On Sept. sixteenth, Zacks Analysis Director Sheraz Mian shared his earnings look-ahead.
Key factors:
(1) Complete S&P 500 earnings are at the moment anticipated to extend +24.0% from the identical interval final 12 months on +11.3% increased revenues.
14 of the 16 Zacks sectors are anticipated to get pleasure from constructive earnings progress, and 6 sectors produce double-digit progress.
This would be the most broad-based earnings progress efficiency in current occasions.
(2) The revisions development stays constructive, sustaining the favorable revisions development that has been in place for a 12 months now.
Because the begin of Q3-26, earnings estimates have moved increased for half of the 16 Zacks sectors.
(3) With Conglomerates (-35.4%) as the one Zacks sector anticipated to have decrease Q3 earnings relative to the year-earlier interval, the quarter is on monitor to provide an impressively broad-based progress efficiency.
Q3 will even be the eighth straight quarter of double-digit earnings progress for the S&P500 index.
(4) Zacks #2 Rank (BUY) Micron (MU – Free Report) and Zacks #1 Rank (STRONG BUY) Nvidia (NVDA – Free Report) proceed to be materials contributors to the Tech sector’s progress image.
Excluding these two firms?
Q3 earnings for the remainder of the Tech sector can be +23.7% (vs. +42.0% in any other case).
That’s all for this International Week Forward.
Glad buying and selling and investing!
John Clean, PhD.
Zacks Chief Fairness Strategist and Economist